

What's Really Behind a Card Swipe
Gateway, processor, merchant account, POS: learn what each piece of your payment setup does, how they fit together, and why it matters to your business.

Oct 27, 2026 · By Barry L. Prentice
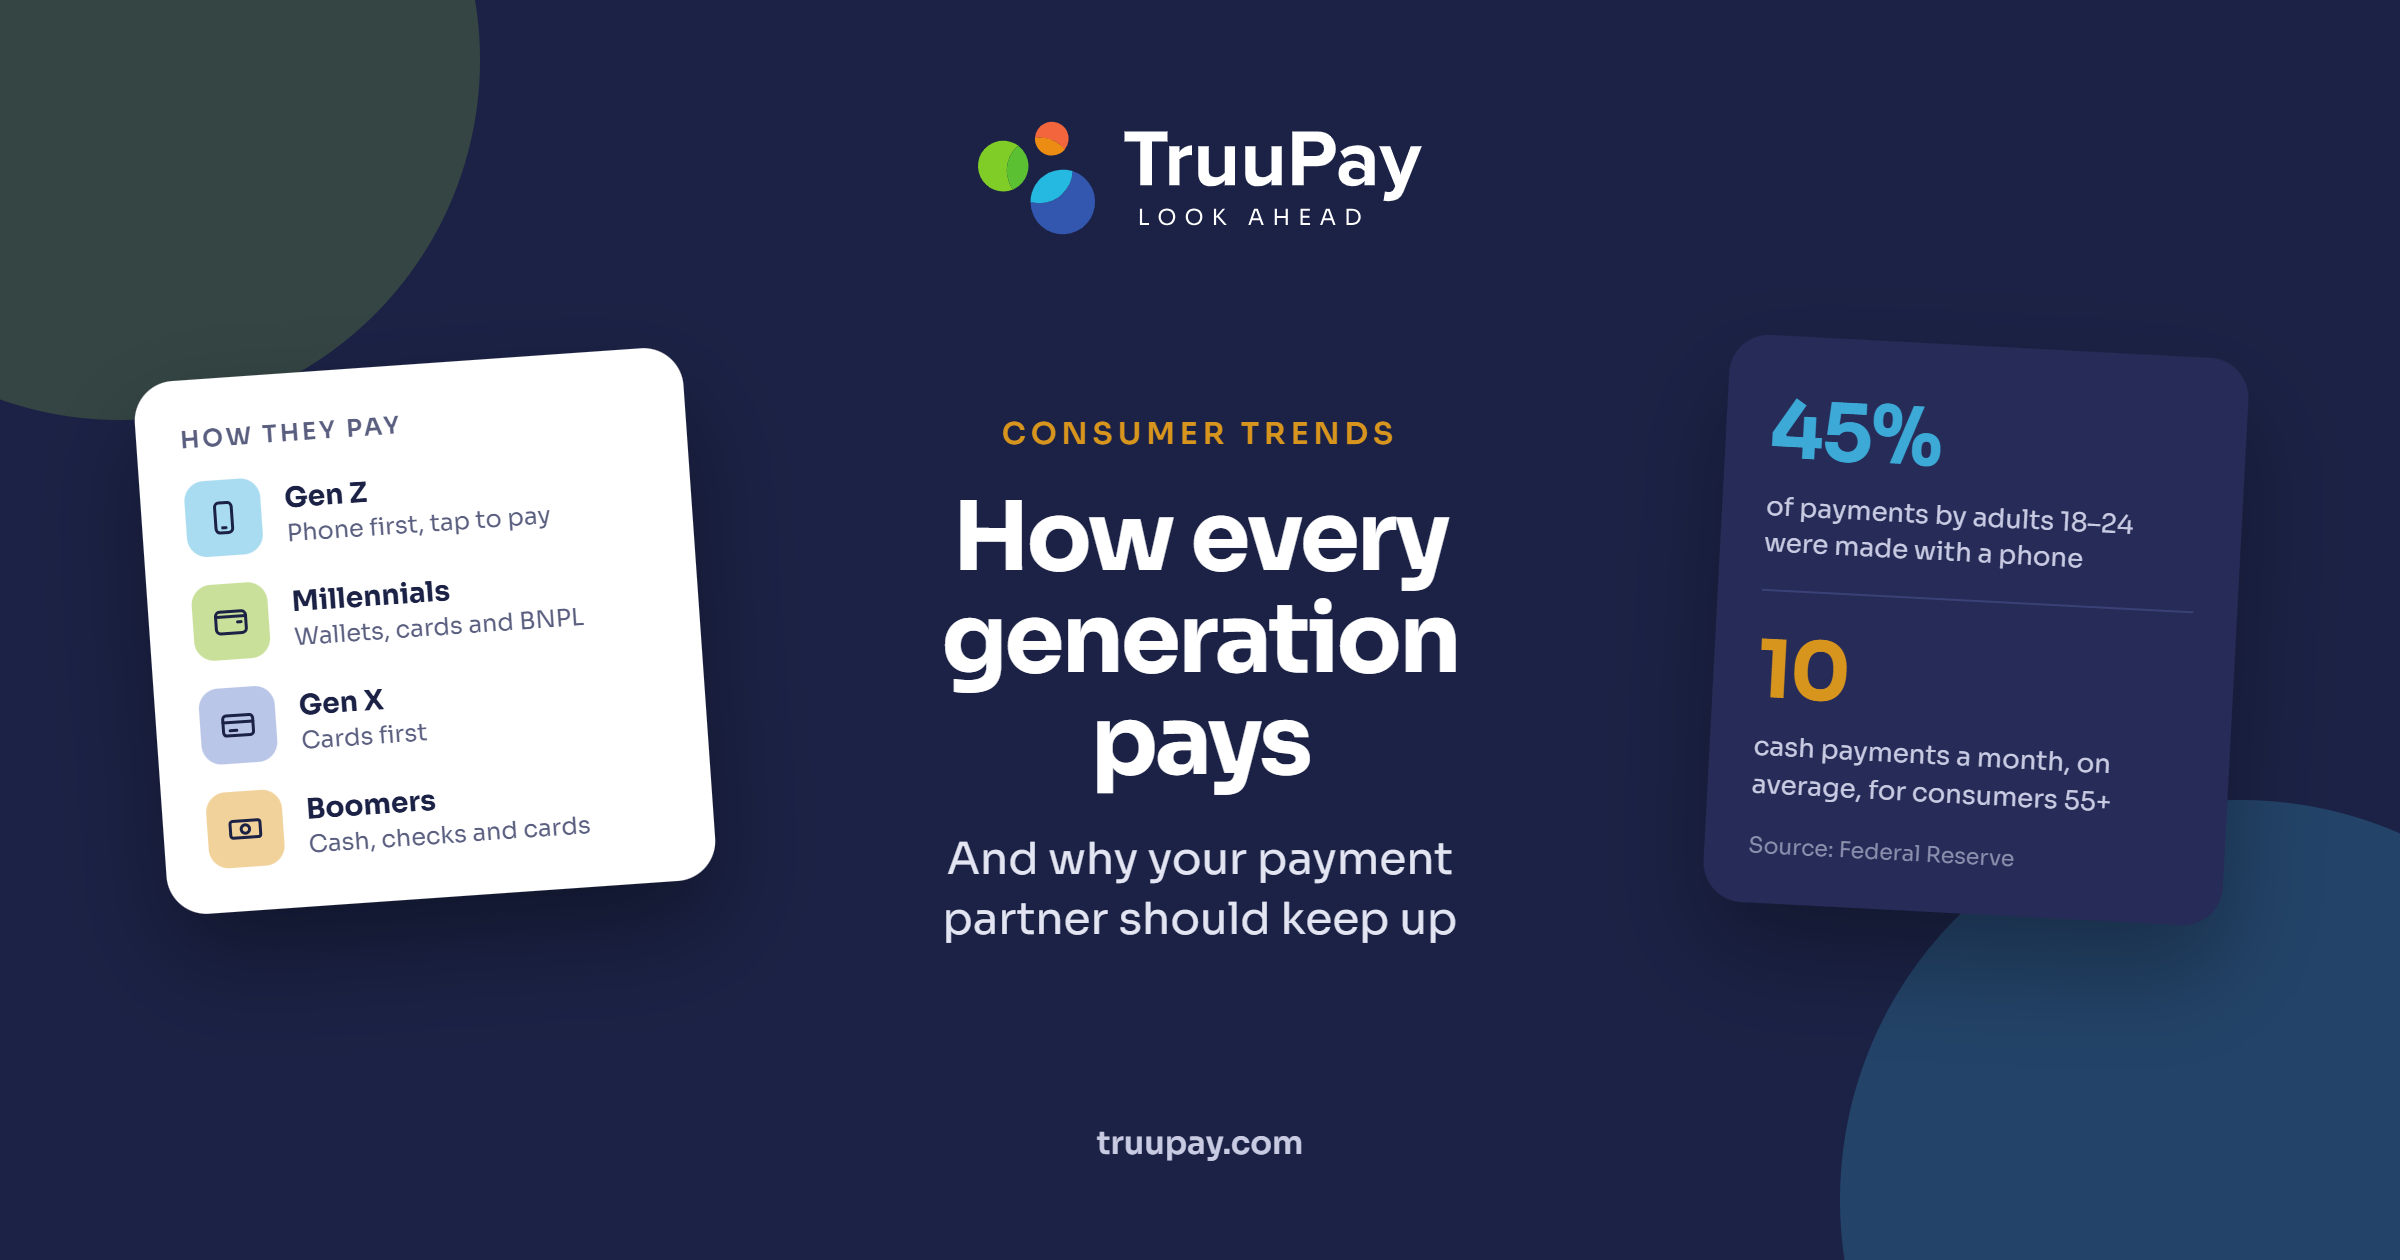
Your customers don't all reach for the same thing at checkout. A 22-year-old taps a phone. A 45-year-old swipes a debit card. A 68-year-old may still count out bills. Every one of them expects you to take their money the way they prefer to give it.
The data backs this up. In the Federal Reserve's latest Diary of Consumer Payment Choice, consumers 55 and older averaged 10 cash payments a month, while those 18 to 24 averaged just two (Federal Reserve Financial Services, 2026). The Fed also notes that age and other demographics have become more tied to how people pay over the past decade, not less.
For a business owner, that means the payment setup that worked five years ago may be quietly turning customers away today. Here's how each generation pays, and what it means for the processing partner behind your counter and your website.
Gen Z grew up with a smartphone in hand, and they pay like it. The Fed found that adults 18 to 24 paid with a mobile phone for 45% of all their payments (Federal Reserve Financial Services). A LendingTree survey found 84% of Gen Z had used a mobile wallet to make a purchase (Chain Store Age).
What they expect at checkout:
The risk of ignoring them is real. PYMNTS found that 28% of Gen Z either abandoned an online cart because a wallet wasn't accepted or said they would have (PYMNTS).
Millennials helped make digital commerce normal, and they use more ways to pay than any other group. Yet cards are still the foundation underneath it all. PYMNTS describes a generation that mixes wallets, apps and pay-later options, but keeps coming back to credit and debit (PYMNTS).
A few things stand out:
Millennials are also in their peak earning and household-building years. They're often the customer with the biggest ticket.
Gen X is the bridge generation. They're comfortable online, but their default is still a plastic card. PYMNTS found debit and credit cards funded 81% of Gen X's most recent store purchases (PYMNTS, October 2026). Velera's research also names debit as this group's preferred method (Velera).
That doesn't mean they ignore newer options. Gen X will use a wallet or an installment plan when the benefit is clear:
What wins Gen X over is reliability and security. A checkout that works every time, with no surprises, earns their loyalty.
Boomers have the most established habits, and cash is still a real part of them. Consumers 55 and older make about five times as many monthly cash payments as the youngest adults (Federal Reserve Financial Services, 2026). Research from the Federal Reserve Board also shows cash and check use rising steadily with age (Federal Reserve Board).
But it's a mistake to assume Boomers won't go digital:
Velera sums it up well: Boomers will adopt a new tool once it clearly adds value (Velera). For merchants, that means keeping traditional options open while making newer ones easy to try.
Most businesses don't serve just one generation. A restaurant, a salon or an online store sees all four in the same week. The goal isn't to pick a favorite. It's to make sure no customer hits a dead end at checkout.
That comes down to a few practical moves:
The cost of a gap is lost sales. In the LendingTree survey, 37% of mobile wallet users said they had stopped shopping somewhere that didn't accept digital payments (Chain Store Age).
You can't serve every generation if your processor only covers some of them. Your payment partner decides which cards you can take, whether your terminal accepts tap-to-pay, how smooth your online checkout is, and how fast new options reach your business.
When you evaluate a processing partner, ask:
At TruuPay, that's the conversation we have with every merchant. We look at who your customers are and how they want to pay, then build a setup that fits. And because we work with multiple processing relationships and sponsor banks, we're not forcing your business into a one-size-fits-all solution.
Your customers already know how they want to pay. Let's make sure you're ready for all of them. Reach out at truupay.com, email info@truupay.com, or call 866-941-3806.
We specialize in bespoke solutions for hard-to-place merchants, offering tailored support and fast approvals. Our team ensures you have the secure, efficient payment processes needed to succeed.
As a reseller, you work hard to secure the right providers to reduce your clients’ risks. We make your job easier by accepting all payments under one roof, so that you have more free time to grow your business.
Sign up for email updates and receive expert insights, industry trends, and exclusive updates!